01
Whole-market access
A curated universe across strategic acquirers, aggregators, private equity, lenders, peer RIAs, and internal-succession financing. No single-firm agenda and no mandate to sell.
Flagship Research & Analysis
READ NOWH1 2026, State of Advisor MovementThe State of Financial Advisor Movement, H1 2026
Read Now
Liquidity and legacy, on your terms. A private options review, a defensible valuation, a curated list of qualified buyers and capital partners, and a competitive process run at your pace. Retire-in-place programs priced against the open market before you sign either.
In one paragraph
Winthrop & Co. is a sell-side succession advisor for financial advisors and RIA owners. We value the practice, price every path on the same after-tax basis, including retire-in-place programs, internal succession, sell-and-stay, minority capital, and a full sale, curate the qualified buyers and capital partners, structure the terms around what the owner keeps, and run a confidential, competitive process from readiness to close. Engagements are buyer-funded or success-based. Owners who run the analysis and decide to stay owe nothing.
Strategic buyers, consolidators, private-equity-backed platforms, banks, peer RIAs, and lenders are competing for practices, and the prices reflect it: the median RIA transaction set a record in 2025, and the two most active quarters ever recorded landed in the first half of 2026. For many owners there is a moment when the business is bigger than one person, when clients rely on it, staff depend on it, and the industry is moving faster than the owner can or wants to scale alone.
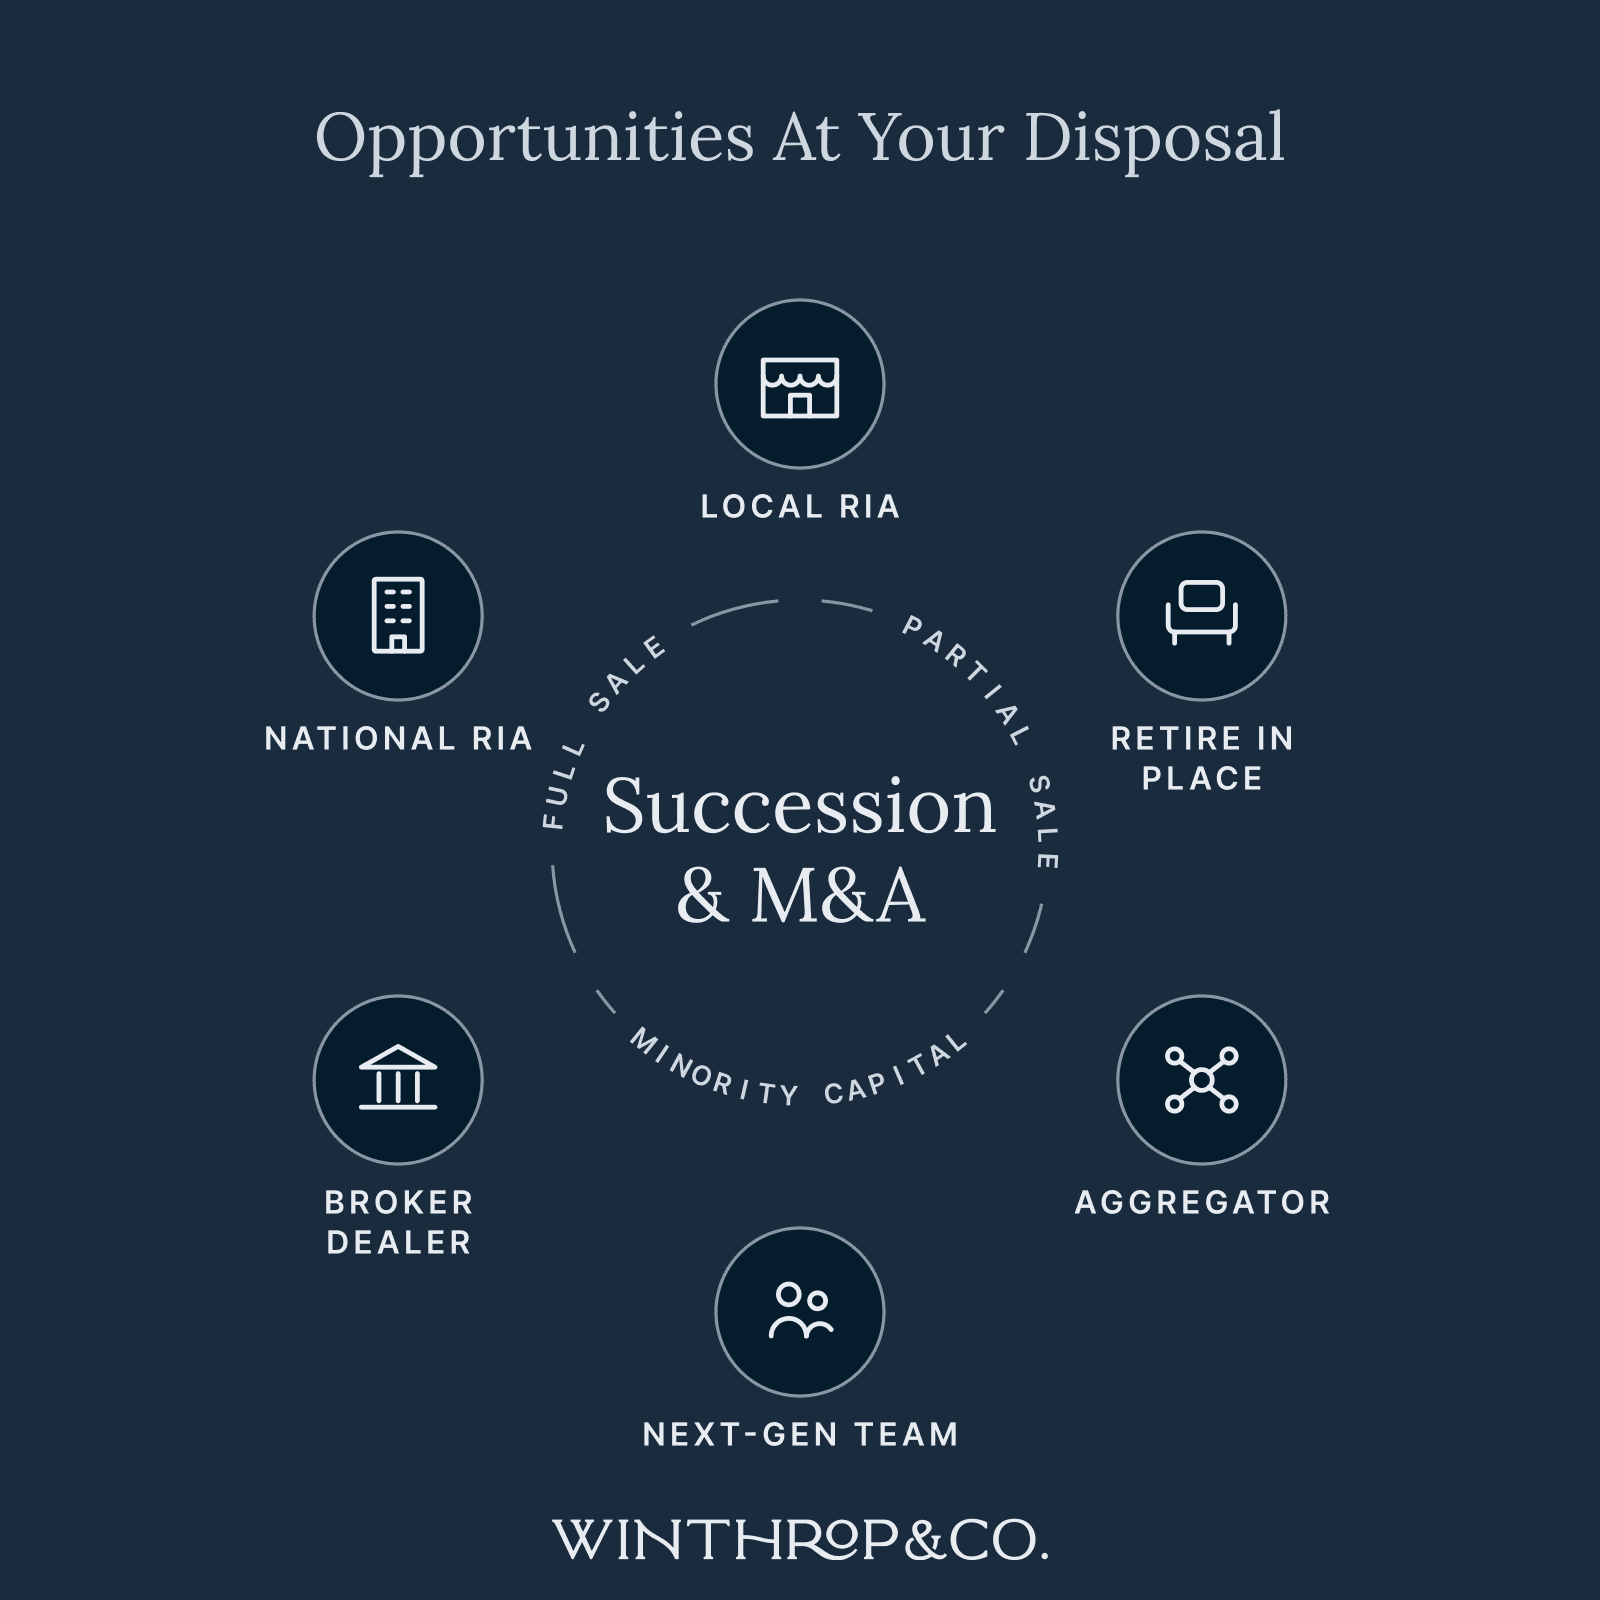
That is when succession stops being a someday topic and becomes an enterprise decision: sell, merge, take minority capital, use debt to buy time and capacity, hand the practice to the next generation, or retire in place. Each path pays differently, taxes differently, and leaves the owner with a different amount of control. Roughly a third of advisors expect to retire within ten years, and a quarter of them have no plan; we wrote about what that looks like from the inside in succession without a successor.
The best outcomes start before any letter of intent, by putting every path on one page and pricing it honestly. That is the options review, and it is where every engagement begins.
Free guide
The RIA M&A Landscape: 2026 Edition
The four buyer types and what each pays for, the multiple ladder band by band, how 2026 deals are structured, and the seller's process from readiness to close.
Get the guideThe six paths
Every succession lands in one of these six. The options review prices all of them on the same after-tax, all-in basis for your practice; this is the shape of the trade in each.
Retire in place at your current firm
What you get
A defined multiple of trailing production paid over a transition period, no market process, continued employment.
What you give up
Successor chosen by the firm, a non-compete, ordinary-income treatment, and no sale of the asset.
Internal succession to your team
What you get
Continuity for clients and staff, control over the handoff, a legacy inside the firm you built.
What you give up
Usually the lowest price, and financing that must be designed years early because most successors cannot pay today's values.
Sell-and-stay to a peer or platform RIA
What you get
Liquidity now, a chosen successor, and a paid transition period in which clients meet the next advisor while you are still in the chair.
What you give up
Employment terms after the sale, and some autonomy negotiated in the paper.
Minority capital or debt
What you get
Partial liquidity and growth funding while you keep control; often the bridge that lets an internal successor buy in.
What you give up
A partner in the cap table, and a future liquidity event you will need to plan for as well.
Majority sale to a consolidator or PE-backed platform
What you get
The highest headline multiple in the market and the deepest structure menu.
What you give up
Control, a share of the price in equity and earnout, and exposure to the sponsor's exit clock.
Sale to a bank or strategic acquirer
What you get
Cash-heavy consideration and a buyer paying for geography or capability rather than a platform thesis.
What you give up
Integration into a larger institution, and a client experience that changes more than it does under an RIA buyer.
Market-level ranges, for orientation: standalone RIA firms traded at a record median 11.6x adjusted EBITDA in 2025; practices under a broker-dealer umbrella trade at roughly 1.5x to 3x recurring revenue; sunset programs typically pay a multiple of trailing production over a transition period. What a specific practice commands is worked through in what is your book actually worth and the scale premium.
Read the fine print
Every large firm now runs a sunset program that pays a retiring advisor a multiple of trailing production over a final tour of duty. They are the path of least resistance, which is exactly why they deserve a hard look before you sign. The successor is chosen by the firm, a non-compete is attached, the payout is ordinary income, and no asset changes hands. At the top production tiers they can be genuinely competitive. Below those tiers, measured against an open market that transfers ownership with successor choice and capital-gains treatment, they are often the most expensive convenience an advisor accepts.
We put your in-house option side by side with sell-and-stay, majority sale, minority capital, and non-dilutive financing for an internal buyout, on one after-tax basis. The goal is not to push a move. It is to quantify what you gain or give up so you choose with eyes open. The framework is in sunset program or sell, and the rent-or-own arithmetic behind it is excerpted from our movement report in Rent or Own: Sunset Programs vs the Market.
Your firm's program, read closely
Edward Jones
The retire-in-place program, priced from the firm's own documents.
Merrill Lynch
The retire-in-place program, priced from the firm's own documents.
Northwestern Mutual
The retire-in-place program, priced from the firm's own documents.
UBS
The retire-in-place program, priced from the firm's own documents.
How we work
Five stages, in order. Many owners stop after the second one, better informed and owing nothing, and come back when the practice is ready.
01
Success criteria, timing, and a valuation and proceeds model built on your revenue mix, margins, growth, retention, and risk. If the practice is two years from ready, this is where we say so.
02
Your in-house option, including any retire-in-place program, priced side by side with the open-market paths on the same after-tax, all-in basis. Staying is modeled as seriously as selling.
03
A short list of qualified counterparties that fit your size, mix, and goals: consolidators, PE-backed platforms, peer RIAs, banks, lenders, and internal-succession financing. NDA first, outreach you control.
04
Cash, equity, earnout, and rollover sized so you de-risk while keeping upside that actually pays. Decision rights, investment policy, branding, titles, and comp for your team written into the terms.
05
Diligence choreographed, client communications sequenced, and day-one transition planned so the deal works after it closes. A competitive process typically runs 90 to 150 days from readiness to close.
Why us
A curated universe across strategic acquirers, aggregators, private equity, lenders, peer RIAs, and internal-succession financing. No single-firm agenda and no mandate to sell.
Valuation and proceeds modeling, structure scenarios, and term-sheet design that go beyond the headline multiple to what you actually keep.
Readiness, buyer outreach, diligence choreography, and day-one transition planning so the deal works after it closes, for clients and for staff.
NDA first, controlled outreach, and a communications framework that protects client relationships until you decide what is shared and when.
Typically buyer-funded or success-based. No retainers and no exclusives to explore your options.
Advisory lineage tied to more than $250B in client assets guided across the industry, and the movement research the industry itself cites.
FAQ
The questions owners actually ask in a first conversation, answered the way we answer them there. For the market context, The State of Financial Advisor Movement carries the demographic and valuation data behind every answer.
Do the reading first
Succession without a successor
What an advisor with no buyer and no junior partner actually does: the key-person test, the first document, and five paths.
The succession crisis, by the numbers
106,000 advisors retiring, a trainee pipeline that is not replacing them, and what scarcity does to prices.
The G2 problem
Why the valuations that made founders wealthy priced their own successors out of buying the firm.
What is your book actually worth?
How buyers actually price an advisory practice, and why the same book carries two different numbers.
Sunset program or sell?
Retire-in-place versus the open market, priced as the two different transactions they are.
The scale premium
Multiples by size, where the premium comes from, and the point where building scale stops paying.
What you can expect next
A valuation, every path priced on one after-tax basis, and a short list of qualified counterparties. Then a competitive process at your pace, or the decision to keep building, owing nothing either way.